
Will Homeowner’s Insurance Pay for a New Roof in Louisiana? (And When It Won’t)
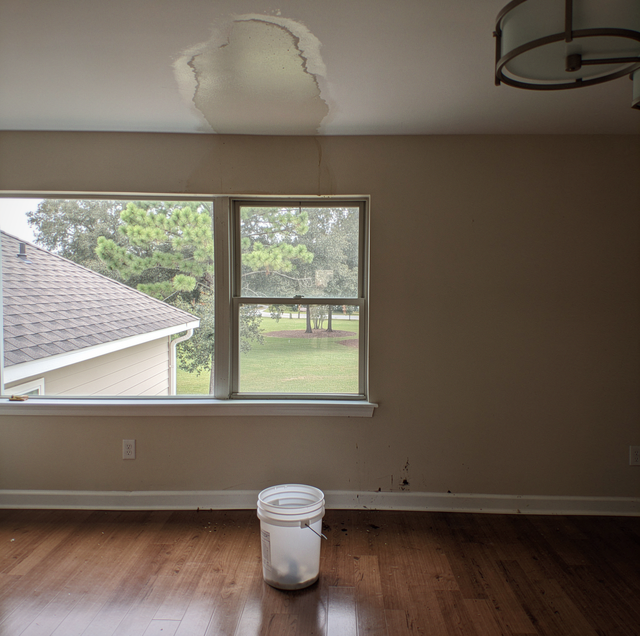
Water shows up in the bedroom ceiling after the last storm. Or the insurance agent flags the roof at Water appears on the bedroom ceiling after the last storm. Or the insurance agent flags the roof at renewal and warns about non-renewal. Either way, the homeowner is trying to figure out whether the carrier will write a check for a new roof or hand the bill back.
The honest answer depends on details most homeowners do not know to ask about. ACV vs. RCV. Roof-payment schedules. Hurricane deductibles. The Louisiana Annual Deductible Law. Whether the carrier is admitted or surplus lines. This is the walk-through every Northshore homeowner needs in plain English.
The Three Questions That Decide Everything
Before calling the carrier, before climbing up, and before signing anything — the claim's outcome comes down to three questions:
1. What caused the damage? Storm and falling-object damage are covered. Wear and tear is not — ever. The first question every adjuster asks is which side of that line the damage falls on.
2. How old is the roof? Newer roofs get paid out at full replacement value. Older roofs trigger depreciation deductions, payment schedules, and sometimes outright denial.
3. How is the policy actually written? "Standard homeowners insurance" covers a wide range of roof scenarios, from generous to almost worthless. The endorsements on the declarations page do most of the work.
Cause of Damage — The Bright Line Between Claim and Denial
Every Louisiana homeowner's policy excludes wear and tear. Everyone. That is not a carrier difference; it is a category. Damage from gradual deterioration — UV degradation, sealant failure, granule loss from age, brittle shingles snapping — is the homeowner's responsibility to repair. Always.
What insurance does cover: sudden, accidental, identifiable events. A hurricane peels shingles off in clusters. Hail dents and cracks the surface. Wind lifts a section of decking. A tree limb punches through. Lightning splits a rafter. These are claim events.
The gray zone is where most disputes happen. A leak appears six months after a storm. The roof is 14 years old. The shingles show both wear and wind damage. The adjuster's job is to determine the cause.
Documentation is what puts that determination on solid ground.
Roof Age — Why a 5-Year-Old Roof and a 15-Year-Old Roof Are Different Conversations
• Carriers track roof age aggressively. Roof age affects whether claims pay full value, whether the policy renews at all, and which endorsements the carrier requires. There is no single statewide rule — every carrier sets its own thresholds — but the patterns are consistent across Louisiana admitted insurers.
• Roofs under 10 years and in good condition usually qualify for Replacement Cost Value (RCV) coverage. Documented maintenance helps. The wind/hail premium is at its lowest, the discount for an impact-rated roof applies, and the carrier is happy to renew.
• Roofs 10-14 years old enter the gray zone. Some carriers shift the policy to a roof-payment schedule that caps payouts by age bracket. Others keep RCV but require an inspection before renewal. Premiums rise. The discount for any future upgrades becomes more important.
• Roofs 15+ years old face stricter underwriting. Many admitted carriers will not renew without a passing inspection. ACV (Actual Cash Value) becomes the default. Some markets non-renew automatically at age 20. Documentation of recent maintenance — boot replacements, flashing re-seals, granule checks — is what keeps the policy on the same terms.
ACV vs. RCV vs. Payment Schedule — The Math Most Homeowners Get Wrong
Three coverage bases determine what a carrier actually pays for a covered roof loss. The differences can be five-figure swings on the same damaged roof.
• Replacement Cost Value (RCV). Pays the cost to replace the damaged roof with new materials, minus the deductible. Usually paid in two parts: the depreciated amount upfront, then the depreciation "holdback" once the work is completed and receipts submitted. Best case for the homeowner.
• Actual Cash Value (ACV). Pays the replacement cost minus depreciation tied to the roof's age and condition, then minus the deductible. The carrier's depreciation calculation can be aggressive — a 15-year-old shingle roof might be depreciated 50% or more.
• Roof-payment schedule. Some Louisiana policies use a fixed schedule by age: 100% for the newest roofs, then stepping down (e.g., 80%, 60%, 40%) by bracket. Applied after the deductible. Hard cap on the collectible amount — the bracket controls the maximum.
• Same $20,000 roof. Different policy structures. Different settlement.
The "hybrid" option in the last row is the one most homeowners miss when buying a policy. Many Louisiana carriers offer lower premiums by writing the dwelling at RCV but the roof at ACV. The savings look attractive at the quote. The math on a real claim does not.
The Louisiana Hurricane Deductible — How $7,000 Becomes the First Out-of-Pocket Hit
The standard homeowners' deductible is usually $1,000-$2,500. The hurricane deductible is different. It is a separate, higher deductible that triggers when a hurricane or a named tropical storm causes damage. Along the Gulf Coast, it is almost always written as a percentage of Coverage A — the dwelling limit — rather than a flat dollar amount.
Typical Louisiana hurricane deductibles run 2% to 5% of dwelling coverage. On a $300,000 home with a 2% deductible, the homeowner pays $6,000 out of pocket; at a 5% deductible, the same scenario climbs to $15,000. Roof age does not erase that deductible — it changes how the roof portion is paid after the deductible is met.
There is a Louisiana-specific protection most homeowners do not know about. La R.S. 22:1337 — the Annual Deductible Law, passed in 2009 after the back-to-back devastation of Katrina/Rita and Gustav/Ike — caps the hurricane deductible at one per calendar year for owner-occupied one- and two-family homes.
How it works in practice: if Hurricane A causes $4,000 of damage and the full hurricane deductible is paid, then Hurricane B hits the same year and causes $12,000, only the unpaid portion of the deductible remains owed. The carrier covers the rest. This is real money in an active hurricane season.
How to File a Claim That Doesn't Get Denied
The order matters. Most denied claims fail in the first 48 hours, not the back-and-forth with the adjuster weeks later. This is the sequence Epic walks Northshore homeowners through.
Step 1 — Document before doing anything else
Date-stamped exterior photos of every visible damage location. Wide shots showing the whole house. Close-ups of damaged shingles, lifted flashing, and missing pieces. Interior photos of ceiling stains, drips, and water on floors. Video the active drip if there is one. A safe roof walk produces the best detail, but most documentation works with binoculars or a drone from the ground.
Step 2 — File within the policy window
Most Louisiana policies require notice within 30-90 days of the loss event. Some require notice within 24-48 hours for emergency mitigation coverage. Check the declarations page or call the agent immediately. Filing notice does not commit the homeowner to anything — it preserves the right to claim.
Step 3 — Stabilize, but don't permanently repair
Tarp the active leak. Move furniture. Pull saturated drywall to prevent mold. These are covered emergency mitigation expenses, and the policy expects them. What not to do: replace shingles, re-flash a chimney, or do permanent roof work before the adjuster sees it. Permanent repairs before adjuster inspection let the carrier argue the damage is not what was claimed.
Step 4 — Get an independent inspection
Hire a licensed roofer to inspect and write a report independently of the carrier's adjuster. The two reports get compared. When they agree, the claim resolves quickly. When they disagree, the homeowner's documented report is what gives them standing. Many Northshore roofers, including Epic Roofing, do this inspection free for storm-damaged homes.
Step 5 — Compare estimates
The carrier's adjuster writes an estimate. The homeowner's roofer writes an estimate. They will not match. Standard practice is for the contractor to send a supplemental request to the carrier listing specific items the adjuster missed or underpaid. Most disputes resolve here — adjusters are open to documented supplemental requests, especially with photos.
Step 6 — Escalate if denied or underpaid
If the carrier denies the claim or underpays significantly, the homeowner's options are: hire a public adjuster (in Louisiana, hourly fees only — contingency contracts are prohibited under La R.S. 22:1703(A)), file a complaint with the Louisiana Department of Insurance (1-800-259-5300), or consult an attorney for bad faith claims. Louisiana has stronger bad-faith insurance protections than most states.
When Insurance Won't Pay — and What to Do Instead
• Some claims will be denied. Knowing the categories ahead of time helps the homeowner decide whether to pursue a claim, accept a denial, or find a different path to a new roof.
• Wear and tear leaks. Pipe boots cracked from UV. Flashing sealant aged out. Granule loss from 20 years of sun. Every Louisiana policy excludes these. Filing only adds to the claims history without paying anything.
• Maintenance failures. Leaks from clogged gutters, debris-dammed valleys, and ice from frozen downspouts (rare here). Insurer's argument: the damage was preventable. Usually denied.
• Cosmetic-only damage. Hail bruising on shingles that do not yet leak. Some carriers cover this as functional damage, others exclude it explicitly with a "cosmetic damage exclusion" endorsement. Check the policy.
• Roofs past the age threshold with no documentable storm event. A 22-year-old roof leaks. There is no recent named storm. The insurer says the roof is at the end of life — wear and tear, not covered.
What to do instead in these cases: cash pay (often combined with financing), targeted repair instead of full replacement, or a FORTIFIED upgrade that pays itself back via the mandatory Louisiana insurance discount. Sometimes the FORTIFIED route makes more sense than fighting a denied claim.
Documentation Worth Having Ready Before Hurricane Season
Most homeowners scramble for paperwork after a storm. The ones who collect it during the calm season win every dispute that follows.
• Proof of roof age. The permit or final inspection date for the last roof replacement. The contractor invoice. Manufacturer warranty registration. Any of these proves the roof's age definitively.
• Maintenance and repair records. Every invoice for boot replacements, flashing re-seals, leak fixes, and ventilation upgrades. Even small invoices count — they show ongoing care.
• Pre-storm photo set. Every spring, walk the perimeter with a phone. Photograph every roof slope, the eaves, ridge, valleys, step flashing, and plumbing vents. Photograph the attic — especially around any past leak repairs. These photos establish the "before" state.
• Policy declarations and endorsements. The pages that mention roof, wind/hail, ACV/RCV, or any schedule. Knowing what is on the policy before a claim starts beats reading it while filing one.
A roof claim that gets paid in full looks the same as a roof claim that gets denied — until the documentation comes out. The homeowners who win Louisiana roof claims know the policy before the storm hits, document the damage the moment it appears, and get an independent inspection before the adjuster shows up. Order matters. Slowing down for the first 48 hours lets the rest of the claim run itself.